Wealthy individuals often confuse insurance with a type of investment that should bring profits or exceed market performance. This misconception overlooks what insurance is really for: it’s not meant to increase your wealth, but rather to protect the assets you’ve built over time. The true importance of insurance is in stopping significant losses that could destroy years of financial achievements.
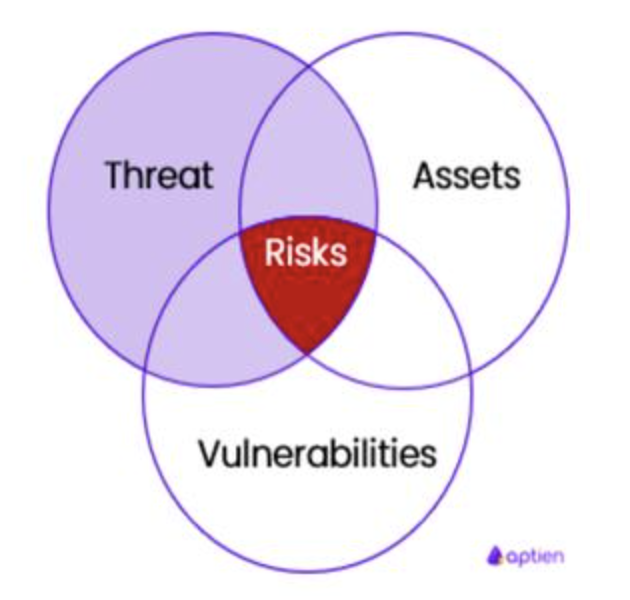
Asset Segregation: Walling Off Vulnerabilities
Affluent people encounter specific risks such as lawsuits, changes in the market, and financial declines. Having insurance helps to separate your essential assets from possible liabilities. For instance, a well-designed umbrella policy doesn't yield profits but safeguards personal wealth against lawsuits that surpass standard liability limits—this protection is especially vital for those in high-risk professions, including doctors, business owners, or corporate leaders. Likewise, the cash value in permanent life insurance held in irrevocable trusts typically has protection from creditors, which keeps your capital safe even amidst business collapses or unfavorable legal decisions. While these measures may not generate income, they act as strong defenses for your wealth.
Business Continuity: Safeguarding Income Streams
For business owners and entrepreneurs, personal wealth is closely linked to how well their companies do. Key person insurance doesn't pay out dividends, but it helps a business continue if important leaders are lost. Should a founder or major executive die unexpectedly, the payment from the policy helps with costs for hiring, keeps operations steady, or supports buy-sell agreements—stopping the need to sell off assets or shut down the business, which could severely harm personal wealth. This safeguard helps keep the income flowing that supports your wealth, even during times of leadership difficulties.
Legacy Preservation: Avoiding Forced Liquidation
For affluent families, estate taxes and probate expenses can reduce inheritances by 30-50%, but life insurance addresses this issue quietly. While investments can change in value, a life insurance payout offers quick cash to pay for taxes, legal expenses, and settlement fees. This helps beneficiaries avoid the need to sell businesses, properties, or investments at bad times to cover their tax bills. Although the policy does not generate profit, it safeguards the quality of your wealth distribution, making sure that your legacy is passed on to the rightful heirs whole.
Volatility Mitigation: Stabilizing Portfolio Shocks
Market declines, health crises, or disruptions in industries can significantly hurt investment assets, yet insurance serves as a financial buffer. Policies for income protection compensate for lost wages if you are impacted by illness or disability during your most productive years, thus avoiding the need to withdraw from your portfolio early to meet living costs. Likewise, long-term care insurance protects retirement funds from the high expenses, often exceeding $100,000 annually, associated with specialized care, keeping savings intact for their intended purpose. While these policies might not create growth, they help avoid draining your wealth when other income streams are unavailable.
The true benefit of insurance isn't found in profits or interest—but rather in maintaining the stability of your finances. For individuals who have accumulated substantial wealth, the importance lies in removing severe risks that no investment plan can withstand. Ultimately, insurance doesn't enhance your wealth; it helps preserve it.
